
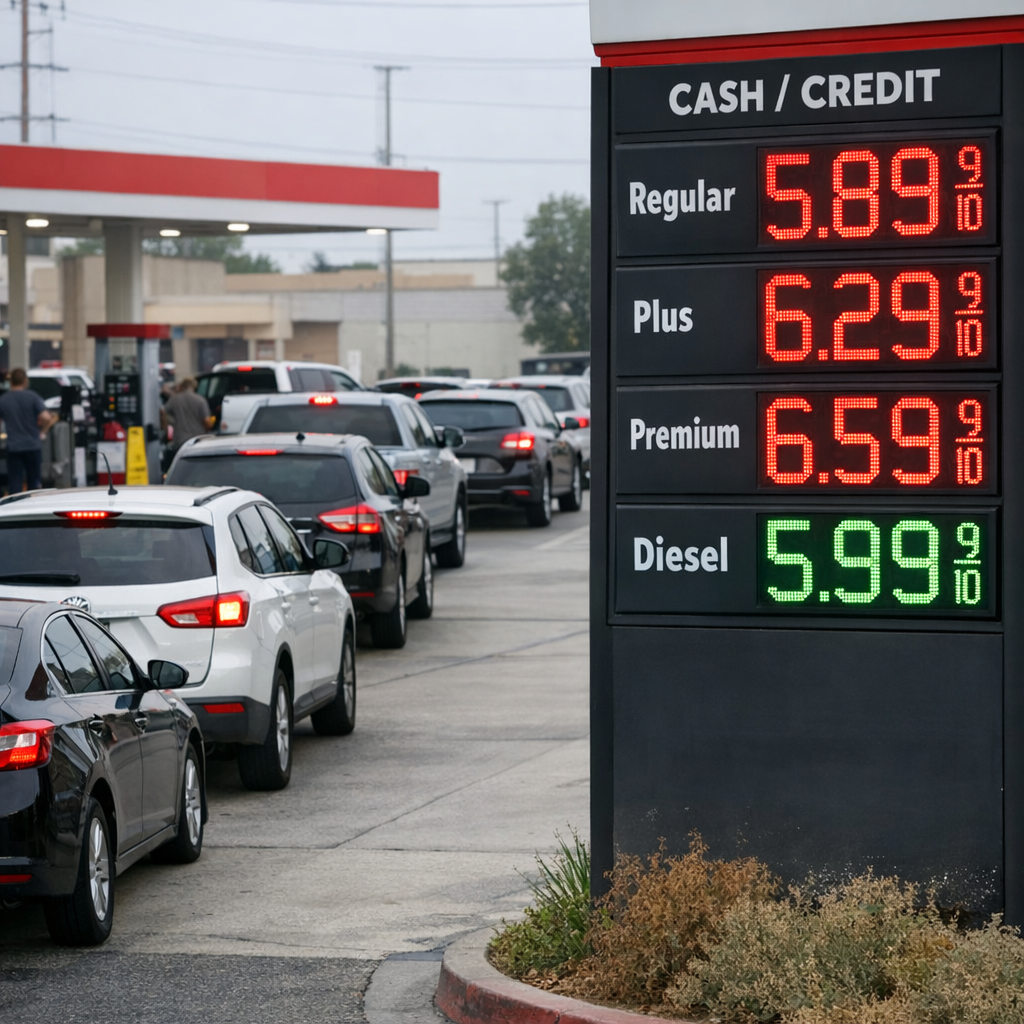
Recent economic indicators have highlighted significant challenges for American households and businesses. Inflation has reached a three-year high, with consumer prices rising 4.2% in May compared to the previous year. This surge is largely driven by escalating energy costs, notably due to geopolitical tensions affecting global oil supply.
Energy prices alone accounted for over 60% of the inflation in May, with gas prices rising due to Iran’s closure of the Strait of Hormuz. This has intensified financial strain on households, whose wages have failed to keep pace. Many families are cutting back on spending, missing credit payments, and turning to dollar stores and savings to cope.
Public sentiment reflects growing concern. A recent poll indicates that only 29% of Americans approve of President Donald Trump’s handling of the economy, marking a record low during his two terms. Additionally, 57% believe the economy is worsening, and only 14% believe it’s improving. These figures underscore the urgency for effective policy responses to address the economic challenges facing the nation.
In response, the Federal Reserve, under new Chair Kevin Warsh, is expected to hold rates steady for now but may lean toward future hikes. Businesses have been affected by higher costs and tariffs imposed in 2025, forcing cutbacks and changing consumer behavior. Despite inflation, job growth remains strong, potentially delaying any Fed rate cuts.
As the nation grapples with these economic pressures, it is crucial for policymakers to implement strategies that alleviate the burden on consumers and foster a more stable economic environment.