
Recent developments in the U.S. economy have introduced a mix of challenges and opportunities for consumers and businesses alike. Understanding these changes is crucial for making informed decisions.
New Tariffs Implemented
The administration has imposed new tariffs ranging from 10% to 12.5% on imports from 60 countries. These measures aim to address concerns over goods produced through forced labor. While intended to promote fair trade, these tariffs may lead to increased prices for imported goods, affecting both consumers and businesses.
Rising Gasoline Prices
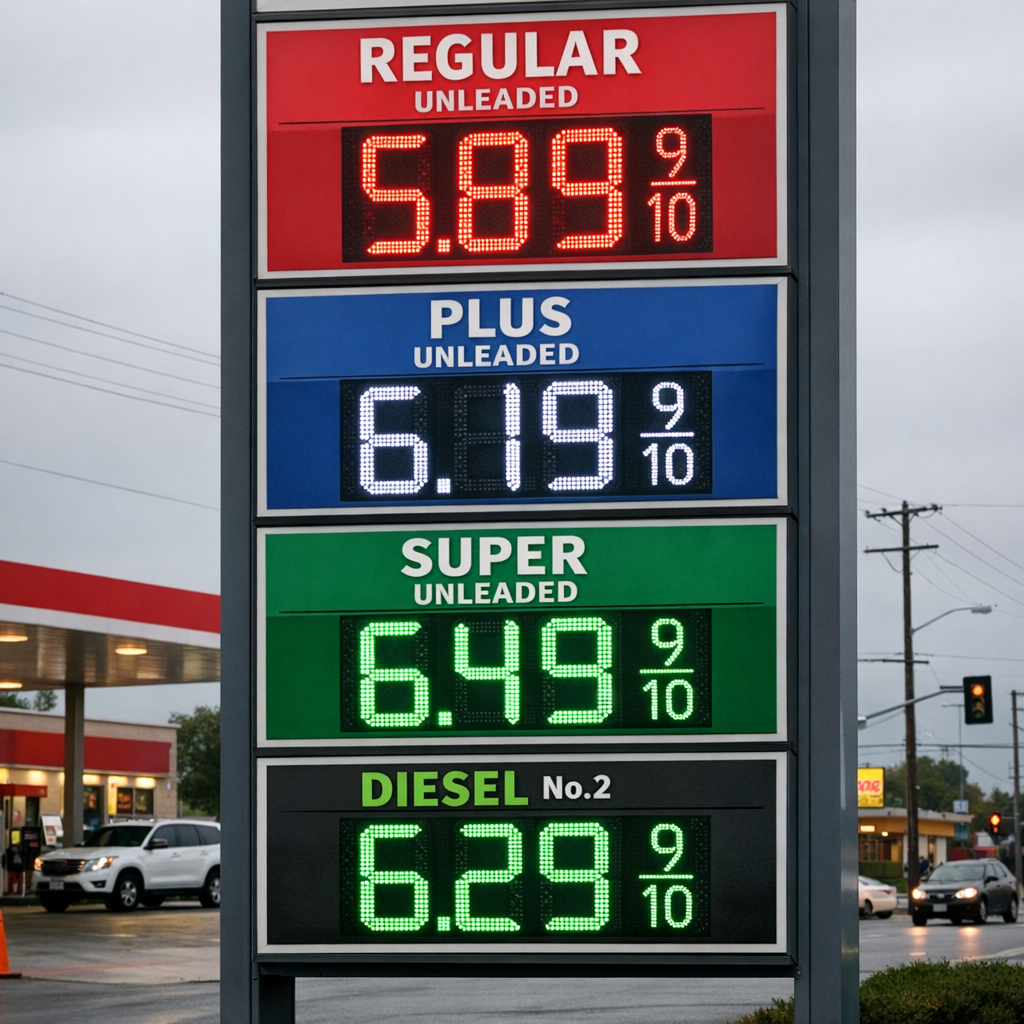
Gasoline prices have surged, with national averages climbing above $4.11 per gallon. This increase is attributed to rising crude oil prices and escalating tensions in the Middle East. Higher fuel costs can impact household budgets and transportation expenses.
Mortgage Rates on the Rise
The average 30-year mortgage rate has increased to 6.58%, the highest level in nearly a year. This uptick may affect prospective homebuyers and those considering refinancing, potentially leading to higher monthly payments.
Employment Trends
On a positive note, jobless claims have dropped to their lowest point since 1969, with only 187,000 new unemployment applications last week. This indicates a resilient labor market, offering some optimism amid other economic challenges.
Staying informed about these developments is essential for navigating the evolving economic landscape. Monitoring these trends can help individuals and businesses make strategic decisions in response to changing conditions.